 Google AI
 ChatGPT
 Perplexity
Right now, 22.7 million renter households pay rent every month. That is according to the Harvard Joint Center for Housing Studies. Nearly half of these families spend more than 30 percent of their income on housing. That is a record high. Millions of people send rent checks like clockwork. They build zero equity in return.
At the same time, investors keep buying homes. Harvard researchers track this trend closely. Investor home purchases hit 28 percent of all sales at the recent peak. That is well above the 16 percent share investors held before the pandemic. Investors are not worried about home prices. They are building wealth, one house at a time.
You have a choice. You can keep paying rent to someone else. Or you can collect rent and build your own equity. To build wealth fast, you need the right tool. For many investors, that tool is a DSCR loan.
This guide shows you how DSCR financing works. You will learn what it costs and how to qualify. You will also learn the steps to buy your first rental and grow from there.
Why Banks Make Growth Hard
Banks make buying a rental home hard. Walk into a local bank and they hand you a stack of paperwork. They want two years of tax returns. They want W-2 forms, pay stubs, and bank statements.
The bank checks your debt to income ratio, or DTI. They add up your car payment, student loans, credit cards, and your own house payment. Then they compare that total to your income.
Why Tax Write-Offs Hurt You at the Bank
If you run your own business, you already know this problem. Good accountants lower your taxable income. That saves you money at tax time. But banks only see that lower number. They may say you do not earn enough, even when your bank account says otherwise.
Banks also cap your growth. Government lenders like Fannie Mae often stop financing you at ten properties. Even if every house makes money, the bank cuts you off.
That is why smart investors use a different tool. They use asset-based financing instead.
How a DSCR Loan Works
DSCR stands for Debt Service Coverage Ratio. It is a simple idea.
A DSCR loan does not look at your job. It does not check your pay stubs or your W-2. It looks at the house. Does the rent cover the mortgage payment? If yes, the loan makes sense. The property qualifies itself.
The Math Behind the Ratio
The formula is simple:
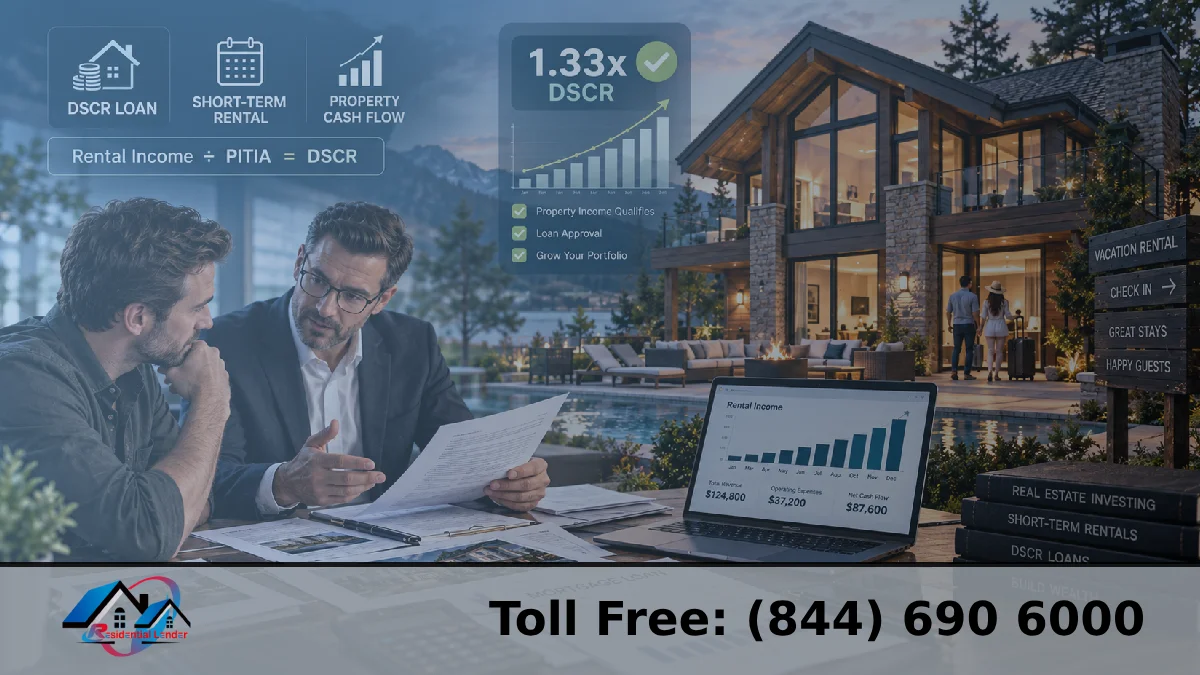
DSCR = Gross Monthly Rent ÷ Monthly PITIA
Gross monthly rent is the rent you collect each month. PITIA is your full mortgage payment. It stands for:
- P: Principal, the loan amount you pay down
- I: Interest, the cost to borrow money
- T: Taxes, your local property tax bill
- I: Insurance, your hazard and flood coverage
- A: Association fees, HOA or condo dues
Say a house rents for $2,500 a month. Your PITIA comes to $2,000. Divide $2,500 by $2,000. You get a DSCR of 1.25. Rent covers the payment with 25 percent to spare. Lenders like that cushion.
| Monthly Rent | Monthly PITIA | DSCR | Result |
| $1,500 | $2,000 | 0.75x | Negative cash flow |
| $2,000 | $2,000 | 1.00x | Breakeven |
| $2,400 | $2,000 | 1.20x | Positive cash flow |
| $2,500 | $2,000 | 1.25x | Strong cash flow |
| $3,000 | $2,000 | 1.50x | High yield cash flow |
What Counts as Rent and PITIA?
Underwriters look at real, steady numbers. They use the lower of two figures: the appraiser’s rent estimate or your signed lease. They do not count surprise repairs. They do not guess at future vacancies. They just check that rent covers the full payment.
Some loans offer an interest-only option. You skip principal payments for a set time. Your payment drops to just ITIA. Your DSCR goes up. More cash stays in your pocket each month.
What Do You Need to Qualify?
You do not need years of landlord experience. Many DSCR programs welcome first-time buyers. You just need to hit a few key numbers.
Down Payment
Every DSCR loan needs skin in the game. Most down payments run 20 to 25 percent of the price. That gives you a loan-to-value ratio of 75 to 80 percent. There is no zero-down option here. Lenders want real equity behind the loan.
On a $300,000 home, 20 percent down is $60,000. Put down 25 percent and that is $75,000. If your DSCR runs low, say 0.85 to 0.90, expect to put down 25 to 30 percent instead.
Credit Score and Cash Reserves
You skip income checks, but your credit score still matters. Here is how it usually breaks down:
- A score of 620 to 660 is the common starting point.
- A score of 680 to 700 gets you better pricing.
- A score of 720 or higher unlocks the best rates and terms.
Lenders also want cash reserves. This is money left in your account after closing. Most want three to six months of PITIA saved up. If your payment is $2,000, six months of reserves means $12,000 in the bank. That cushion proves you can pay the mortgage even if a tenant leaves.
The Appraisal and Rent Report
The appraisal is the biggest step in underwriting. An independent appraiser checks two things.
First, they check the home’s value and condition. The house must be safe and move-in ready. DSCR loans will not fund a major fixer-upper. Small repairs are fine. Bigger deferred repairs usually cannot pass $2,000.
Second, they check fair market rent. The appraiser fills out a Fannie Mae Form 1007. This form compares your home to similar rentals nearby. Say the house already has a tenant. Then the loan team uses the lower of two numbers. That is your lease or the Form 1007 estimate.
Can You Skip Income Verification?
Yes. That is the whole point of no income verification rental loans.
The property’s cash flow replaces your pay stub. Underwriters never ask for your tax transcripts. They never call your boss. They do not care about last year’s write-offs. They check three things only. Does the property earn enough rent? Do you have cash to close plus reserves? Does your credit score show good habits? That is it. This opens the door for business owners, freelancers, and growing investors alike.
What Are DSCR Rates Like Today?
Rates move with the wider mortgage market, so treat any number as a snapshot, not a promise. DSCR rates usually run a bit higher than a standard owner-occupied mortgage. That is the trade-off for skipping income checks. Your own rate depends on a few things. That means your credit score, your down payment, your DSCR, and your property type. A strong borrower with a high score gets better pricing. A big down payment helps too. Ask your lender for a rate sheet early. Then you know your numbers before you write an offer.
DSCR vs. Other Loan Types
DSCR vs. a Conventional Mortgage
Paperwork is the big difference. Conventional loans need tax returns, W-2s, and tight DTI limits. DSCR loans need none of that.
Portfolio size matters too. Conventional loans usually cap out at ten properties. DSCR loans have no such cap. You can also close in an LLC, not just your own name.
Cost is the trade-off. Conventional rates usually run lower. DSCR loans often carry an exit fee too, called a prepayment penalty. A common setup is 3-2-1. Sell or refinance in year one, pay 3 percent of the loan. Do it in year two, pay 2 percent. Do it in year three, pay 1 percent. Some lenders stretch this out over five years. Others offer a “buy-up” option. You take a slightly higher rate. In trade, you skip the penalty. Ask about this if you plan to sell or refinance early.
DSCR vs. Hard Money
Hard money is short-term debt for fix and flip projects. Rates often run 10 to 14 percent. Terms last just 6 to 24 months. It is built for buying and fixing distressed homes fast.
DSCR loans are long-term debt for buy-and-hold investors. You get a 30-year fixed rate or an interest-only period on a move-in ready home. Many investors use both tools together. This is called the BRRRR method: Buy, Rehab, Rent, Refinance, Repeat. You buy a fixer with hard money or a fix and flip loan. You fix it up. You place a tenant. Then you refinance into a long-term DSCR loan.
DSCR vs. LLC Portfolio Loans
Local banks sometimes lend to LLCs too. But they often want personal guarantees. They may ask for full audits of your other businesses. They may add a balloon payment after five or ten years. A DSCR loan skips all of that. Your LLC gets a 30-year fixed loan with no personal income review.
Low-DSCR and No-Ratio Loans
Not every good deal hits a clean 1.25 ratio right away. Some low DSCR ratio deals still make sense. This is common in fast-growing markets, where equity growth matters more than day-one cash flow.
Some lenders offer sub-1.0 DSCR loans. These fit homes where rent falls a bit short of the full payment. Expect a higher rate in exchange. Expect a bigger down payment too. A few lenders skip the ratio check entirely. These “no-ratio” loans qualify you on credit and cash alone. They cost more. But they help investors who want a specific home, no matter what it rents for today.
Pulling Cash Out With a DSCR Refinance
Once a rental builds equity, you can pull that equity out. This is a cash-out DSCR refinance. You take a new loan sized to the home’s current value. You pay off the old loan. You keep the leftover cash.
Many investors use that cash as the down payment on their next deal. One house turns into two. You do not need to save fresh capital from scratch. The same DSCR math still applies. Your rent still needs to cover the new, larger payment.
Blanket Loans for Multiple Rentals
Do you own several rentals already? A blanket loan, also called a portfolio loan, can help. It wraps multiple properties into one note. You get one monthly payment instead of several. This can simplify your paperwork. It can also improve your pricing, since the lender looks at your whole portfolio’s cash flow at once. Ask a lender who handles DSCR loans for rental property if a blanket loan fits your next few deals.
How Fast Does a DSCR Loan Close?
Speed matters in real estate. A good deal will not wait around. Most DSCR loans close in 20 to 30 business days. Compare that to a traditional bank, which often takes 45 to 60 days.
| Phase | Milestone | Working Days | Goal |
| 1 | Application & Review | Days 1 to 3 | Run credit, review bank statements, issue term sheet |
| 2 | Entity Setup | Days 2 to 5 | Confirm LLC, operating agreement, EIN |
| 3 | Appraisal & Rent Schedule | Days 5 to 14 | Appraiser inspects home, delivers Form 1007 |
| 4 | Underwriting & Title | Days 12 to 22 | Title search, insurance review, clear to close |
| 5 | Funding & Closing | Days 20 to 30 | Wire funds, sign docs, close the deal |
A good DSCR lender keeps this timeline on track. They order the appraisal on day one. They work with the title company early. This avoids common delays.
How to Structure Your Deal
Buy Through an LLC
The best way to hold a rental is through an LLC. This keeps your rental business separate from your personal life. If a tenant sues, the lawsuit hits the LLC only. Your savings and your own home stay safe.
Setting up an LLC is simple. File Articles of Organization with your state. Write an Operating Agreement. Get a federal EIN from the IRS. Open a business bank account. Closing your loan in an LLC also keeps your name off public deed records. That adds privacy on top of legal protection.
Buy Rentals Out of State
You do not have to buy near home. Coastal markets often have high prices and thin rental yields. A DSCR loan lets you live in one state and buy in another. A local appraiser checks market rents through Form 1007. A local property manager screens tenants and handles repairs for you.
Multi-Unit Properties Spread Your Risk
Single-family homes are great investments. But small multi-unit buildings offer extra safety. DSCR loans cover duplexes, triplexes, and fourplexes. If one tenant in a single-family home leaves, your income drops to zero. If one tenant in a fourplex leaves, three units still pay rent. Your mortgage stays covered. Multi-unit homes also tend to earn more rent per dollar spent. That helps you clear the 1.25 DSCR mark. You also close on all the units at once. That saves on title fees and appraisal costs.
How to Find the Right DSCR Lender
Not every lender offers DSCR loans. Local banks often do not understand them. Big online mortgage sites focus on owner-occupied buyers. There are three main types of DSCR lenders to know.
Retail banks and credit unions take deposits and lend under strict rules. They want full tax returns. They rarely offer true DSCR financing.
Direct wholesale lenders write DSCR loans directly. But they often have just two or three programs. If your deal falls outside their box, they say no.
Correspondent and table lenders bring deep experience and their own funding lines. A team with 30 years in this business can match your deal to the right program. They do not force it into one rigid rulebook.
A table lender controls the whole process. They review your appraisal. They handle your entity paperwork. They fund the loan through their own money line. A lender with many programs gives you more paths to a closed deal. This includes bridge loans, hard money, ground-up construction, and long-term DSCR loans. Keep in mind, a lender funds your deal. They do not run your rental business. That part is on you.
Step-by-Step: How to Buy Rental House With a DSCR Loan
Step 1: Check your finances. Confirm your credit score meets the lender’s minimum. Pull your last two months of bank statements. Make sure you have enough cash for the down payment, closing costs, and reserves.
Step 2: Form your LLC. Set up your LLC through your state’s website. Get your EIN from the IRS. Write your operating agreement. Open a business checking account.
Step 3: Run the numbers. Screen a few rental properties. Check local rents with a property manager or online listings. Calculate the PITIA. Divide the rent by that number. Make sure your DSCR hits your lender’s target.
Step 4: Make your offer. Submit your purchase contract through your agent. Include an appraisal contingency and a standard inspection window. Once the seller accepts, send your deposit to escrow.
Step 5: Order the appraisal. Your lender sends the appraisal order. The appraiser inspects the home and fills out Form 1007. Underwriting compares that number to your loan amount.
Step 6: Close the loan. Your lender finishes the title work and confirms insurance. You review your closing disclosure, wire your down payment, and sign your loan documents. The house is yours.
Tips to Protect Your DSCR
Closing the loan is just the start. Good management keeps your numbers strong for years.
Screen every tenant. An eviction is expensive and slow. Check credit, past evictions, and employment before you sign a lease.
Build a repair fund. Set aside 5 to 10 percent of your rent each month. When something breaks, you will have cash ready.
Check rents every year. Costs rise over time. Compare your rent to the local market each year and adjust as needed.
Track everything for taxes. Log your income and expenses on IRS Schedule E. Good records mean more deductions and a lower tax bill.
Ready to Get Started?
Millions of families are still renting, and rents keep climbing. Waiting on the sidelines means missing out on real equity.
Banks may slow you down with paperwork and DTI limits. A DSCR loan skips that entirely. The property’s income does the work. Your tax write-offs stay intact. Your personal assets stay protected inside an LLC.
Check your cash reserves. Run your target numbers. Then connect with a DSCR lending team and put this strategy to work on your next deal.
Frequently Asked Questions
Can you live in a DSCR house?
No. DSCR loans fund rentals only. Moving in yourself breaks the loan terms. It can trigger default. Treat the home as a business asset, not your next home.
Can Airbnb income qualify?
Yes. Many lenders accept short-term rental income. For DSCR loans on short-term rentals, lenders often use booking data instead of a lease. Tools like AirDNA help them estimate your income.
Can foreign nationals qualify?
Yes, in most cases. You do not need US citizenship or a US credit file. Lenders focus on the property’s rent and your available cash.
Can you buy an empty house?
Yes. The appraiser sets expected rent using nearby comparable homes. You do not need a signed lease to close.
Can the seller cover closing costs?
Often, yes. Sellers can usually credit a percent of the price toward your costs. Ask your lender what percentage your program allows before you negotiate.